Disputes & Insolvency

Dispute Resolution, Litigation & Insolvency
Lawyers on the
Gold Coast and Northern NSW


Is a dispute, debt or financial pressure causing uncertainty?
Get clear advice before the issue escalates.

Disputes and financial pressure can quickly become stressful, especially when they affect your business, property, finances or peace of mind. Whether the issue involves an unpaid invoice, contract disagreement, lease issue, creditor demand or insolvency concern, getting advice early can help you know where you stand, what your options are and what steps you can take next. At CJM Lawyers, our dispute resolution, litigation and insolvency lawyers provide clear, practical guidance to help clients understand their legal position and move forward with confidence.

Not sure if you have a legal issue?

If any of the situations below sound familiar, you may be dealing with a dispute or insolvency matter. Our team can help you understand your options and take practical steps forward before the matter escalates. These everyday issues may involve different areas of dispute resolution, litigation or insolvency law.

We can help you if you’re:

Owed money, chasing unpaid invoices or being ignored after asking for payment

Being asked to pay an amount you do not agree with or do not understand

Dealing with a disagreement about a contract, quote, invoice, lease, property issue or business arrangement

Unhappy with the quality, timing or completion of goods, services or work

Dealing with issues involving a business partner, shareholder, director, supplier, contractor or another party

Receiving a letter of demand, statutory demand, formal notice or other legal correspondence

Under financial pressure, struggling to meet payment obligations or concerned about insolvency risks

Types of Disputes We Assist With

We assist with matters involving:

Contract and agreement disputes

When terms are unclear, obligations are not being met, or parties disagree about what was agreed

Building and construction disputes

Including defective or incomplete work, delays, payment disputes, contract variations, and disagreements between owners, builders, contractors or subcontractors.

Property and lease disputes

Including disagreements about leases, rent, outgoings, maintenance, boundaries, easements or property use.

Business and commercial disputes

Involving business partners, shareholders, directors, suppliers, contractors or commercial arrangements.

Debt recovery and payment disputes

Including unpaid invoices, overdue accounts, disputed amounts and claims for payment.

Insolvency and financial distress

Including creditor pressure, statutory demands, formal notices, financial difficulty or concerns about meeting payment obligations.

How We Assist

Once we understand your situation, our team can help you work out the most practical way forward. Depending on your matter, we can assist by:

Reviewing contracts, correspondence, notices, invoices or other relevant documents
Explaining your legal position, risks, obligations and available options
Helping you respond to claims, letters of demand, statutory demands or creditor action
Communicating with the other party on your behalf where appropriate
Supporting negotiation, settlement discussions or other dispute resolution pathways
Preparing formal legal steps if the matter cannot be resolved informally
Guiding you through court proceedings or insolvency-related processes where required

Your Questions, Answered

Find answers to common Powers of Attorney & Advance Care Planning questions below. Have a question not covered here? Enquire today to discuss your situation.

  • Do I need a Testamentary Trust Will?

    Not everyone does. Testamentary Trust Wills are often considered where family or financial circumstances are more complex, such as blended families or where beneficiaries may benefit from structured management of assets. Legal advice can help determine whether this option is appropriate for you.

  • How much more complex is a Testamentary Trust Will compared to a basic Will?

    A Testamentary Trust Will involves additional planning and documentation compared to a basic Will. Whether this added complexity is worthwhile depends on your personal, family, and financial circumstances. A complimentary consultation can help determine whether the additional structure is appropriate for your situation.

  • Can a Testamentary Trust Will be updated later?

    Yes. Like any Will, a Testamentary Trust Will can be reviewed and updated as circumstances change. It’s recommended to review your Will after major life events or changes in financial or family circumstances.

Getting Started

If you need practical legal guidance for a dispute, debt recovery matter, litigation issue or insolvency concern, our team is here to help. Tell us about your situation and we will guide you through the next steps.

1

Enquire today

Tell us about the issue, including whether it relates to a contract, unpaid debt, business relationship, property matter, lease, creditor action, statutory demand or financial distress.

2

We’ll book you in

Our team will review your enquiry, ask any follow-up questions if needed, and arrange for the right person to assist with your dispute resolution, litigation, debt recovery or insolvency matter.

3

Meet with us

We will discuss your situation, explain your options and provide clear, practical advice so you understand your legal position, risks and next steps before moving forward.

Our Disputes & Insolvency Team

Our dispute resolution, litigation and insolvency lawyers provide practical support for individuals and businesses dealing with commercial disputes, debt recovery, property disputes, creditor action and financial distress.
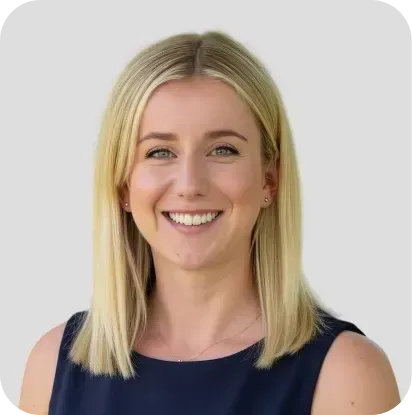
Alexandra Stewart

Alexandra Stewart

Senior Associate

Jack Raward

Jack Raward

Senior Associate

Tansie Higgins

Tansie Higgins

Associate

Our Latest Story
By November 2026 Edition • 5 November 2026
Whether you are preparing for Black Friday, launching an online store or selling online year-round, increased traffic and orders can expose gaps in your terms, pricing, delivery promises and returns processes. If these are unclear or inconsistent with Australian Consumer Law, your business may face complaints, chargebacks and disputes. The following areas provide a practical starting point for checking that customers can clearly understand what they are buying, the total cost, expected delivery and what happens if something goes wrong. Are Your Online Terms Clear and Easy to Find? Online terms should be available before purchase, written in plain English and clearly accepted, such as through a checkout checkbox. They should identify the seller and address orders, payments, stock, cancellations and liability without removing customers’ Australian Consumer Law rights. The appropriate wording will depend on the business’s products, sales process and risks. Are Your Discounts and Price Claims Accurate? Discount claims – including Black Friday promotions, percentage savings, “was/now” pricing, countdowns and limited-stock messages, must be accurate and supportable. New businesses should not claim a previous price unless the product was genuinely offered at that amount, while established retailers should ensure their pricing history supports the saving. Mandatory fees must be included in the total, with other charges disclosed before checkout. Do Your Returns Terms Respect Consumer Guarantees? Discounted goods generally carry the same consumer guarantee rights as full-price goods, so statements such as “no refunds on sale items” cannot exclude remedies for faulty, unsafe or misdescribed products. Returns policies should distinguish these rights from change-of-mind returns and explain how customers can request a remedy without misleading limits or conditions. Can You Meet Your Delivery and Stock Promises? High order volumes can place pressure on stock and delivery systems. Website information and fulfilment terms should use realistic estimates and reflect how the business handles delays, unavailable stock, pre-orders and damaged parcels. The appropriate approach depends on the products, delivery providers and promises made to customers. Could Any of Your Terms Be Unfair? Standard terms should not give the business broad rights while leaving customers with few protections. Clauses allowing the seller to change prices, cancel orders, substitute products or avoid responsibility without a reasonable basis may be unfair. Whether a term is fair depends on its wording, the business’s legitimate interests, its effect on the customer and the contract as a whole. Are Customer Information and Marketing Consents Handled Properly? Online sales and promotional campaigns may involve email sign-ups, abandoned-cart messages, website tracking and customer information. Businesses should check whether the Privacy Act applies and ensure relevant privacy policies explain how information is collected, used, disclosed and protected. Marketing messages, including Black Friday campaigns, must also meet applicable consent and unsubscribe requirements. What Should You Review Before the Sale Goes Live? Before launching a store or major campaign, test the customer journey from advertising to post-sale support. Ensure promotional claims, product pages, prices, stock and delivery information are accurate, and that terms, policies, communications and business processes are consistent. A legal review can identify gaps that may not be obvious internally. These issues are a starting point, not a compliance assessment. Required terms and policies depend on the business model, products, customers, sales channels and campaign promises. Tailored advice can identify the obligations and risks that apply. How CJM Lawyers Can Help CJM Lawyers can prepare ecommerce terms, returns and refund policies, privacy policies and promotional terms for new stores or review the current policies for established businesses. We also advise on Australian Consumer Law, unfair contract terms, complaints and online sales disputes. Arrange a legal health check before your next campaign to help protect your business, reduce disputes and give customers confidence to buy. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By November 2026 Edition • 5 November 2026
Running an equine business involves legal risks as well as the day-to-day care of horses and clients. Whether you operate a riding school, agistment property, breeding program, horse training business, transport service or equestrian facility, the right agreements, safety procedures and business protections can help reduce disputes and protect the people and horses in your care. The right documents and procedures will depend on how your business operates, but the following five essentials are a practical starting point for reducing uncertainty and managing common risks. 1. Written Agreements for Your Equine Business Verbal arrangements can leave important details open to disagreement. A written agreement should clearly explain the service being provided, fees and payment terms, each party’s responsibilities, cancellation or termination rights, dispute processes and what happens if circumstances change. The terms should be tailored to the business. An agistment agreement may need to address feed, veterinary treatment, emergency authority, access, overdue fees and abandoned horses. A training, sale, lease, breeding or transport agreement will involve different risks. Templates copied from another business or downloaded online may not reflect your services, location, legal obligations or unique circumstances, limiting their ability to address your specific risks. 2. Safety Policies and Risk Procedures Horses can be unpredictable, and equine workplaces may expose workers, clients, volunteers and visitors to risks including falls, kicks, bites, vehicles, machinery and unsafe facilities. Businesses should identify hazards, assess risks, implement suitable controls and review those controls regularly. Practical records may include safety inductions, safe work procedures, incident reports, emergency plans, horse suitability assessments and rules for helmets, supervision and facility use. A waiver or acknowledgement of risk, and safety signage may support this framework, but it should not be treated as a substitute for meeting work health and safety and other legal duties. It is highly recommended for equine businesses to take out appropriate insurance cover to protect their operations. Generally, your insurer will want to review copies of your agreements and safety policies and plans. We have experience working alongside clients to ensure their safety documents are compliant with those requirements. 3. Clear Employment and Contractor Arrangements Equine businesses often engage employees, casual workers, instructors, riders, farriers and other contractors. Calling someone a contractor does not necessarily make them one – the way the arrangement works in practice also matters. Since the Closing Loopholes reforms there is a statutory “whole of the relationship” test for characterising employment. If a worker is incorrectly treated as a contractor, the business may become liable for unpaid wages, leave, superannuation and penalties. Written employment or contractor agreements should set out the role, payment, hours or deliverables, use of equipment, confidentiality, intellectual property, insurance requirements and how the arrangement may end. Businesses should also keep required employment records and review whether workplace laws, awards and workers compensation obligations apply. Having your staffing arrangements assessed early can also help identify any discrepancies and potential exposure points before a claim is made or years of back-payments become due. 4. Appropriate Insurance and Asset Arrangements Insurance should be reviewed against the activities the business actually undertakes. Depending on the operation, relevant cover may include public liability, professional indemnity, workers compensation, property, motor vehicle, care, custody and control of horses, business interruption and cover for specific events or activities. Specific insurance policies can be taken out over horses themselves, and in some circumstances, you may require your clients to hold insurance over horses in your care. An overall risk assessment of your business is useful in determining which avenue is most practical for you. Business owners should understand exclusions, disclosure obligations and any conditions attached to cover. Ownership and use of valuable horses, vehicles, equipment and facilities should also be documented, particularly where assets are personally owned, leased to the business, shared with another operator or held through a separate entity. 5. Record-Keeping, Privacy and Continuity Plans Good records can be critical when a payment, injury, horse condition or service is disputed. Keep signed agreements, invoices, attendance and staff records, horse care instructions, veterinary authorities, incident reports and important communications in a secure and organised system. Equine businesses that collect personal information should check whether privacy laws apply to them. Even if an exemption is available, personal information should be collected, stored, accessed and disposed of carefully, with these practices documented in an appropriate privacy policy and, where relevant, the business’s terms and conditions. Businesses should also have a continuity or succession plan identifying who can make urgent decisions, access records, care for horses and keep the business operating if an owner or key person is unavailable. When Should These Documents Be Reviewed? Legal documents should be reviewed when the business adds a new service, changes premises, hires staff, takes on contractors, begins holding horses for clients, purchases major assets or changes its business structure. A review may also be needed after an incident, dispute or insurance change, or when legislation affecting the business is updated. How CJM Lawyers Can Help CJM Lawyers can review how your equine business operates and prepare practical legal documents tailored to your services and risks. Our equine law services include client agreements, agistment and horse-related contracts, employment and contractor arrangements, business structures, property and asset agreements, risk documentation and dispute resolution. If your equine business relies on informal arrangements, borrowed templates or documents that no longer reflect how you operate, contact CJM Lawyers to arrange a legal review. Putting the right foundations in place now may help prevent misunderstandings, protect valuable relationships and make future issues easier to manage. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By October 2026 Edition • 8 October 2026
Cash flow pressure, overdue tax and unpaid suppliers can build gradually, leaving company directors unsure whether the business is experiencing a temporary setback or may be insolvent. Recognising the warning signs and seeking advice early may preserve more options and help directors reduce their personal risk. A company is generally insolvent when it cannot pay its debts as and when they fall due. Financial difficulty does not always mean a business must close, but delays in seeking advice can reduce the restructuring options available, increase business losses and expose company directors to greater personal risk. Business Owner vs Company Director: What’s the Difference? A business owner is someone who owns all or part of a business, while a company director is formally appointed to manage a company and has specific legal responsibilities. In many small businesses, the owner is also a director, but this is not always the case – for example, a sole trader is a business owner but not a company director. Company directors are expected to stay informed about the company’s financial position and take action when warning signs emerge. Ignoring the problem or continuing to incur debts without a realistic ability to pay them may expose directors to serious consequences. Common Warning Signs of Insolvency Warning signs may include ongoing losses, poor cash flow, overdue tax or superannuation, suppliers being paid outside normal terms, increasing debt, difficulty collecting money owed to the business, reliance on personal funds, incomplete financial records, payment arrangements with selected creditors, demands or court documents and suppliers moving the company to cash-on-delivery terms. No single warning sign necessarily proves insolvency. However, directors should seek an immediate review of the company’s financial position when several signs occur together, debts cannot be paid on time or the company is relying on new borrowing or personal funds to meet existing obligations. What Are a Company Director’s Responsibilities? Company directors must understand the company’s operations and financial position, ensure proper records are kept and prevent the company from trading while insolvent. If insolvency is suspected, directors should investigate promptly and obtain appropriate accounting and legal advice. Directors should not rely solely on current bank balances. Cash flow forecasts, debts falling due, tax obligations, employee entitlements, available finance and the realistic recoverability of money owed to the company may all be relevant.  What Can Happen If a Company Trades While Insolvent? Continuing to incur debts while insolvent can lead to civil penalties, compensation claims and, in serious cases, criminal consequences. Directors may also face scrutiny over transactions made shortly before an external administration, including payments that unfairly favour one creditor or transfers that remove company assets for less than their true value. What Should Company Directors Do First? Company directors should bring the company’s financial records up to date, prepare a realistic cash flow forecast and identify debts that are already overdue or will shortly fall due. This information can help professional advisers assess whether the company can continue trading and which restructuring or external administration options may remain available. Directors should also avoid selectively paying creditors or transferring assets without advice, as those transactions may later be challenged. Professional advice should be sought before entering new commitments, using personal funds, granting security, selling assets or agreeing to arrangements that may affect creditors. Could the Business Be Restructured? Depending on the company’s circumstances, options may include informal negotiations with creditors, safe harbour planning, small business restructuring, voluntary administration or liquidation. The most appropriate pathway will depend on whether the underlying business is viable, the level and type of debt, available assets and the support of key stakeholders. Early advice is important because some options require careful planning and may no longer be available once the company has exhausted its cash or creditor support. How CJM Lawyers Can Help CJM Lawyers can advise company directors experiencing financial distress, assess legal risk, explain restructuring and external administration options and work alongside accountants and registered insolvency practitioners. We can also assist with creditor negotiations, statutory demands, court proceedings and disputes involving liquidators or company transactions. If your company is struggling to pay debts when they fall due, has overdue tax or superannuation, or is relying on personal funds to meet ongoing expenses, contact CJM Lawyers early. Timely advice may help clarify whether the company is insolvent, preserve restructuring options and reduce the risk of the situation becoming more difficult to manage. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
Show More

Our Client's Say

Exceptional service
very helpful
Handling issues