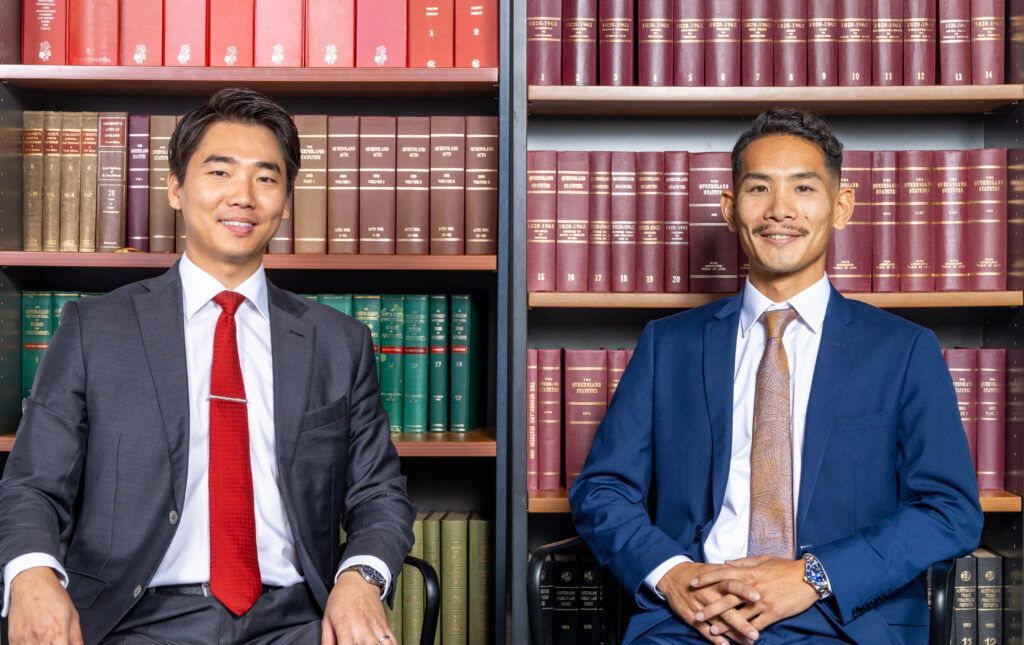
Discussion between a used car dealer and a lawyer.
Nichigo Press
Yusuke Hayata and Jake John

Yusuke Soda and Jake Jeong

Due to its vast territory, Australia is basically a car-based society. People who live in cities may not be particularly conscious of it, but once you leave the city, there are many places you can't go without a car, and a car becomes a necessity. As a result, there is active buying and selling of used cars in Australia at prices that are affordable for working holidaymakers and students. This article introduces Yusuke Soda, the representative of WISE JAPAN, which has its main office on the Gold Coast and has an overwhelming presence as a used car dealer, and Jake Jeong, of CJM Lawyers, a law firm with four offices in QLD and NSW, who talked about the pitfalls of private car sales and the reason for the existence of dealers, including the laws related to used car transactions and how to avoid problems.
Yusuke Hayata and Jake John

 What are the benefits and risks of privately selling used cars? 

While new car sales are rapidly increasing in Australia, the market is declining as used cars, which had been selling well due to replacement demand for new cars, are becoming duplicated, especially older models. As prices continue to drop and it becomes easier to purchase, private sales of used cars tend to become more active.

What do you think?


Yusuke Soda: Don't forget that there are risks associated with individual buying and selling. The higher the risk, the cheaper you can get a car, and the more you spend, the lower the risk.


Jake Jeong: Of course, buying a used car through a dealer is more expensive than buying it privately, but there are obvious reasons why. One of the things that you can do is confirm that the car is sound and safe, including the registration and certificates that are essential when owning a car, the preparation of necessary documents that must be submitted to the government, and mechanical aspects.


Yusuke Soda: When you buy a car from a dealer, safety is guaranteed, so you can ask for help if it breaks down or an accident occurs. The biggest legal difference is whether or not there is a warranty. A common pattern in private sales is that you may find out after the purchase that there was an accident in the past or that the car was stolen. You are obligated to inform the purchaser. In the case of privately sold cars, there is a risk of various problems such as the accident history not being known, and odometer and registration fraud. However, dealers are subject to regulations, so they must not only inform the buyer of the accident history, but also take care of warranty and insurance procedures.


Jake Jeong: Many people don't know information about warranties. Some people, especially those who come to Australia from overseas, don't know whether they need insurance or not and think they don't need it. Meanwhile, dealers provide support by providing important information, including insurance, in addition to the car itself. In the case of a private sale, there is no traceability history or guarantee, such as whether the car is stolen, and everything must be confirmed by the individual. Many foreigners, including Japanese, don't know how to get verified in Australia. For example, if your car has a personal loan on it, you won't legally have the power to take it away, but you could be subject to a claim. There have been many cases where a car that was being financed was sold and its registration was on PPSR, but because the car was sold privately, the car was not known, and the car was repossessed by the bank after the car was acquired.


Yusuke Soda: Certainly. I hear stories like that often.


Jake Jeong: Sometimes it's a stolen car. For example, if your car was stolen the day before you bought it, it may not show up in your car history right away. There is also the risk of being involved in a crime, such as when a car is bought or sold during a police investigation, and after you buy it at a low price, the police investigate and say, ”This is the car you stole.'' In the case of private sales, such risks are extremely high. Since buying a car is a big purchase, it's easy to get careless if you only focus on the low price. It is important to consider carefully, including the level of risk.


Yusuke Soda: I think there are quite a few people who know a lot about cars who think they should just look for one and buy it themselves, but there are people who have a background as mechanics or who worked for an automaker. People who really understand cars buy cars through official shops and dealers. Cars are machines, so they will break down at some point and it will cost money to repair them. This is because we fully understand this. If you buy from a dealer, you have someone to complain to if something goes wrong with your car. If your car breaks down or you're in an accident, you can call your dealer and get help. No matter how much you know about cars, it is difficult to know about insurance, registration, accident history, theft history, etc., so it may be natural for even people who know a lot about cars to think about buying from a dealer.


Jake Jeong: When you buy from a dealer, you get a legal warranty, right? For example, if a used car is 10 years old and has a mileage of 160,000 km or more, there is a one-month warranty period, and if it is less than 10 years old and has a mileage of less than 160,000 km, it will come with a 3-month warranty.


Yusuke Soda: Even if a dealer says they offer a one-year warranty, in reality, the legal guarantee is at most three months for used cars. Many people have this misunderstanding, but even though it says a one-year warranty, it only covers the automatic engine and does not cover everything else, so you need to look carefully at the warranty details.
Yusuke Hayata and Jake John

Jake Jeong: One of the most common incidents recently in private car sales is scams. Specifically, this applies to advertisements posted on the Internet, such as SNS timelines. There are plenty of photos and information about the car, and the link looks legitimate at first glance. After that, when I contacted them, I was asked to pay a deposit before inspecting the car, and after I paid the money, the advertisement disappeared and I was unable to contact the poster.


Yusuke Soda: Most of the people who fall for such scams, such as car and rent bonds, are foreigners. When it comes to cars, be careful about extremely cheap cars. For example, a very new car costs $5,000. Anyone who has lived in Australia with common sense would know that it's strange that a car is being sold at that price, but since they just arrived in Australia and don't speak much English, they just jumped at it because it was a cheap and good car. I transfer the money I have on hand. We also receive inquiries from customers who say that their car broke on the way home after they bought it, or that the engine won't start the next day. There are some small tricks that can be used to keep a worn-out car running for a day or a week. In that case, you would end up buying a piece of scrap metal for $5,000.


Jake Jeong: In the case of scams, there are many cases where you don't know who the recipient is and only know their phone number. Anyone can easily create a Facebook profile, so you should be careful.


Yusuke Soda: There's nothing you can do about it even if you report it to the police, so the only thing you can do is make sure you don't get caught in the first place. To do this, you need the right knowledge, and even if you have that knowledge, there will still be risks, so it's best not to cross dangerous bridges in the first place. I think it's fine to buy and sell cars between people with clear identities, such as good friends, but since there's no dealer in between, if something happens, both parties will be responsible. For example, if something goes wrong with your car, you could have had it fixed for free if you had bought it at a dealer, but because you bought it from a friend, it might cost you $5,000 to fix it. Even in cases where the seller was not expecting this or the buyer had heard that it was a decent car, problems still occur. Also, if the car is too worn out, it may not pass vehicle inspection, and there are some cases where the name cannot be changed. The cheaper the car, the more problems there are.
Yusuke Hayata and Jake John

How can I avoid risks and purchase a used car with peace of mind?

Jake Jeong: When you buy a car privately, you are responsible. You are responsible for everything, including whether you have financing or if there is a problem with your car. Dealers are professionals who also know legal matters related to cars. You can avoid trouble by consulting with your dealer from the beginning, but if you do get into trouble, it would be a good idea to consult a lawyer.


Yusuke Soda: When you buy a car from a dealer, the law comes with a warranty for a certain period of time. At WISE JAPAN, we provide support even if a problem that is not covered by the warranty occurs. We're in business with a signboard, so we do everything we can to support the customers who buy from us. As for warranties, some people offer extended warranties for two years, for example, but that is a product sold as a package. Apart from that, there is a warranty that you must attach as a dealer, and it is divided into two patterns. For older cars that are more than 10 years old and have driven more than 160,000 km, the period is 1 month, and for other cars it is 3 months. Also, we only sell Japanese cars, so that may be another difference between us and other companies.


Jake Jeong: I think you should leave it to a dealer who is familiar with the Australian system. Many people from overseas think that the compulsory insurance on the register covers everything, but it does not cover damage to third parties or damage to assets. That's why I think it's important to get proper information and get insurance.
Yusuke Hayata and Jake John

The important thing is to find out if the dealer is reliable.

Yusuke Soda: The scariest thing is unlicensed people pretending to be dealers. There are actually people who call themselves dealers and do business without a license. There are no guarantees if something happens, so if you run away, it's over. A car is a big machine, but unlike a house, it's surprisingly easy to buy if you save up money. That is why it is important to determine the means of purchase.


Jake Jeong: Even new cars can have problems, so you should be more careful when buying a used car.


Yusuke Soda: What's important is not what model year and car you buy, but where you buy it from. What is important is whether the person you gave the money to will treat you properly even after receiving the money. The key to finding a reliable dealer is whether or not they have a dealer license and a store. Although this is a special case, there are some individuals who simply obtain a license and set up a shop at home. Unlike underground dealers, these dealers are individual dealers, but since they don't have a store, they buy one car on their own, make a small profit, and then sell the car. Therefore, if we decide to issue a warranty, we will not be able to respond if three vehicles arrive at the same time. Another concern is that they don't have the financial strength because they don't have a store. In addition, people who are called black dealers, behind-the-scenes dealers, and backyard dealers do not have licenses or maintenance facilities. Their common pattern is to use someone else's name and sell from someone else's name to someone else's name.


Jake Jeong: To find out, first ask if they have a dealer license. There is a register for each state in Australia, so there is a way to check, and if you do a little research you can find the information. You can tell that the dealer is a legitimate dealer if they have a website, are doing proper marketing, and can check all the information on the register.


Yusuke Soda: Even though they know it's suspicious, there are many people who take advantage of the low price and buy it, but once the car stops working, it's over. I would like you to think carefully and consider the future, rather than jumping in just because it's cheap.


──Thank you very much for today.
Yusuke Hayata

Wise Japan

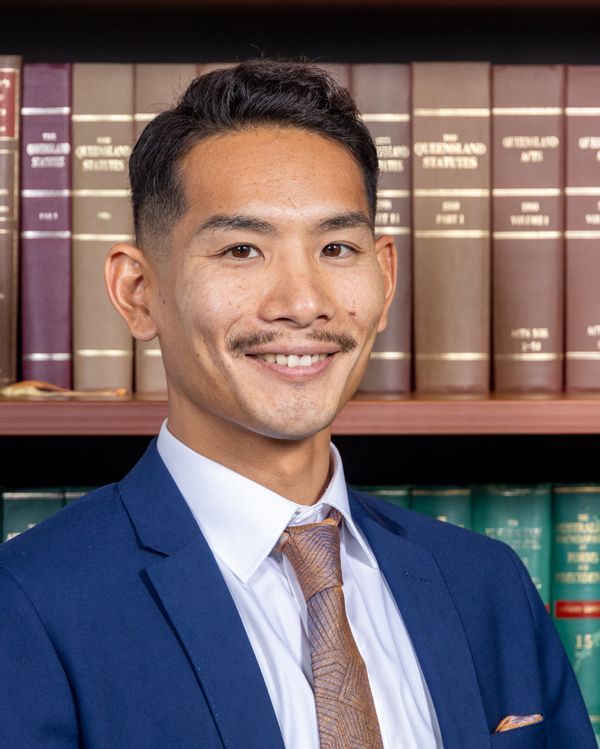
Yusuke Soda

Born in 1993 in Fukuoka Prefecture. Former professional magician. he is an entrepreneur. My hobby is surfing. He started doing magic when he was in elementary school, and while he was in college, he opened his own shop and became a professional magician. After that, he became an entrepreneur and over 11 years was involved in the launch of 9 companies and 13 stores, including a security system company, a purchasing specialty store, and WISE JAPAN, with total sales of 2.1 billion yen. He comes to work every day with his beloved Dalmatian, Pop, who is 3 years old.
Jake John

CJM LAWYERS

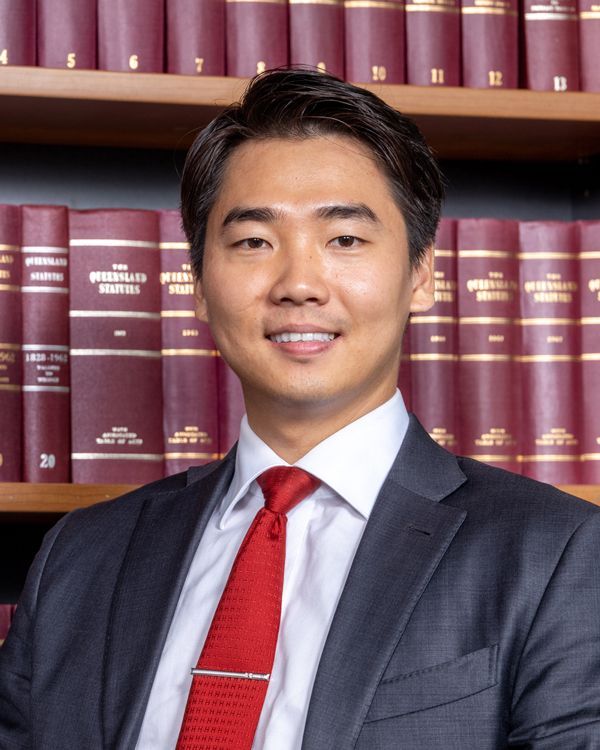
Jake Jeong

Graduated from the Faculty of Law at Bond University. He is admitted to the NSW Supreme Court and the High Court of Australia. He handles a wide range of areas including general civil matters, immigration law, corporate law, family, property, wills and estate. He is fluent in English, Japanese, and Korean, and obtained a score of 90 on the PTE academic exam (equivalent to IELTS 9.0). He has four years of experience as a director of a consulting company related to nursing care. Member of the NSW Law Society, Gold Coast Japanese Chamber of Commerce and Industry, Asian Australian Lawyers Association, etc.


*The information contained in this article provides a general overview of matters of interest and is intended to apply within Australia only. Additionally, CJM Lawyers is not affiliated with Wise Japan Auto Group or Nichigo Press and remain impartial to provide the best possible service to our clients.
Contact Us Now!

For comprehensive legal services, 
book now for your free initial consultation.

Contact Us

Book Now!

Property & Conveyancing
Guarantor  Advice
Commercial & Business
Wills and Estates
Building Disputes
Employment Law
Corporate & Commercial 
Litigation
Regulatory Compliance
Immigration
Litigation
Insolvency & Bankruptcy

Contact Us Now!

For comprehensive legal services, 
book now for your free initial consultation.

Contact Us

Book Us Now!

Property & Conveyancing
Guarantor  Advice
Commercial & Business
Wills and Estates
Building Disputes
Employment Law
Corporate & Commercial 
Litigation
Regulatory Compliance
Retail & commercial leasing, business transactions, company & trust sales, property development, guarantor advice

Our Latest Story

By October 2026 Edition • 8 October 2026
Cash flow pressure, overdue tax and unpaid suppliers can build gradually, leaving company directors unsure whether the business is experiencing a temporary setback or may be insolvent. Recognising the warning signs and seeking advice early may preserve more options and help directors reduce their personal risk. A company is generally insolvent when it cannot pay its debts as and when they fall due. Financial difficulty does not always mean a business must close, but delays in seeking advice can reduce the restructuring options available, increase business losses and expose company directors to greater personal risk. Business Owner vs Company Director: What’s the Difference? A business owner is someone who owns all or part of a business, while a company director is formally appointed to manage a company and has specific legal responsibilities. In many small businesses, the owner is also a director, but this is not always the case – for example, a sole trader is a business owner but not a company director. Company directors are expected to stay informed about the company’s financial position and take action when warning signs emerge. Ignoring the problem or continuing to incur debts without a realistic ability to pay them may expose directors to serious consequences. Common Warning Signs of Insolvency Warning signs may include ongoing losses, poor cash flow, overdue tax or superannuation, suppliers being paid outside normal terms, increasing debt, difficulty collecting money owed to the business, reliance on personal funds, incomplete financial records, payment arrangements with selected creditors, demands or court documents and suppliers moving the company to cash-on-delivery terms. No single warning sign necessarily proves insolvency. However, directors should seek an immediate review of the company’s financial position when several signs occur together, debts cannot be paid on time or the company is relying on new borrowing or personal funds to meet existing obligations. What Are a Company Director’s Responsibilities? Company directors must understand the company’s operations and financial position, ensure proper records are kept and prevent the company from trading while insolvent. If insolvency is suspected, directors should investigate promptly and obtain appropriate accounting and legal advice. Directors should not rely solely on current bank balances. Cash flow forecasts, debts falling due, tax obligations, employee entitlements, available finance and the realistic recoverability of money owed to the company may all be relevant.  What Can Happen If a Company Trades While Insolvent? Continuing to incur debts while insolvent can lead to civil penalties, compensation claims and, in serious cases, criminal consequences. Directors may also face scrutiny over transactions made shortly before an external administration, including payments that unfairly favour one creditor or transfers that remove company assets for less than their true value. What Should Company Directors Do First? Company directors should bring the company’s financial records up to date, prepare a realistic cash flow forecast and identify debts that are already overdue or will shortly fall due. This information can help professional advisers assess whether the company can continue trading and which restructuring or external administration options may remain available. Directors should also avoid selectively paying creditors or transferring assets without advice, as those transactions may later be challenged. Professional advice should be sought before entering new commitments, using personal funds, granting security, selling assets or agreeing to arrangements that may affect creditors. Could the Business Be Restructured? Depending on the company’s circumstances, options may include informal negotiations with creditors, safe harbour planning, small business restructuring, voluntary administration or liquidation. The most appropriate pathway will depend on whether the underlying business is viable, the level and type of debt, available assets and the support of key stakeholders. Early advice is important because some options require careful planning and may no longer be available once the company has exhausted its cash or creditor support. How CJM Lawyers Can Help CJM Lawyers can advise company directors experiencing financial distress, assess legal risk, explain restructuring and external administration options and work alongside accountants and registered insolvency practitioners. We can also assist with creditor negotiations, statutory demands, court proceedings and disputes involving liquidators or company transactions. If your company is struggling to pay debts when they fall due, has overdue tax or superannuation, or is relying on personal funds to meet ongoing expenses, contact CJM Lawyers early. Timely advice may help clarify whether the company is insolvent, preserve restructuring options and reduce the risk of the situation becoming more difficult to manage. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By October 2026 Edition • 8 October 2026
Received a termination notice from your developer? Before accepting a refund or assuming the contract is over, take steps to protect your position. When an off-the-plan development is delayed, a developer may seek to end the sale contract by relying on a sunset clause or another contractual right. The notice can appear final, but whether the termination is valid will depend on the contract, the circumstances surrounding the delay and the steps taken by each party. CJM Lawyers recently acted for a purchaser in successfully disputing a developer’s attempt to terminate an off-the-plan contract relating to the Chevron One development on the Gold Coast. The Queensland Supreme Court declared the contracts valid and binding, verifying why buyers should obtain advice before treating a termination notice as the end of a matter. 1. Do Not Immediately Accept a Refund or Sign Further Documents Accepting the return of your deposit, signing a release or agreeing that the contract has ended may affect the options available to you. Before responding, seek legal advice about what the notice means and whether the developer has a valid right to terminate. 2. Check the Deadline for Responding The notice or contract may contain strict timeframes. Record the date the notice was received and arrange an urgent review so that any response, objection or court application can be considered before a deadline passes. 3. Gather the Contract and All Supporting Documents Locate the signed contract, disclosure material, variations, extension notices, emails, letters and any updates about construction or registration. These documents can help establish what the parties agreed, what caused the delay and whether the required process was followed. 4. Review the Sunset Clause and Termination Wording A sunset date passing does not necessarily mean a developer can automatically cancel. The exact wording of the contract, any notice requirements and the relevant law must be considered together. 5. Create a Timeline of the Development Prepare a simple timeline recording key dates, promised completion dates, extensions, reported causes of delay and communications from the developer. This can help us assess whether the developer contributed to the delay or complied with its obligations. 6. Be Clear About the Outcome You Want Some buyers want the contract to remain on foot so they can complete the purchase. Others may prefer to exit and recover their deposit. Your preferred outcome will help shape the legal and commercial strategy. 7. Obtain Legal Advice Early Early advice can help you understand whether the termination is likely to be valid, identify urgent steps and avoid actions that could weaken your position. Depending on the circumstances, options may include disputing the notice, negotiating with the developer or seeking court orders. How CJM Lawyers Can Help CJM Lawyers can review your off-the-plan contract, termination notice and supporting documents, explain your options and communicate with the developer on your behalf. Our Litigation team can also represent you in negotiations and court proceedings where necessary. If a developer is trying to cancel your off-the-plan contract, contact CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By September 2026 Edition • 10 September 2026
Bought off-the-plan and the developer is trying to cancel your contract? Don’t assume it’s the end of the road. Buying property is exciting, but buying off the plan comes with a unique risk: you are committing to a home or investment before it has been built. If completion is delayed and the developer later tries to walk away from the contract, buyers can be left uncertain about their rights, their deposit and the property they hoped to secure. That issue was recently considered by the Queensland Supreme Court in a case involving Chevron One Apartments on the Gold Coast, Queensland. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Court declared the contracts valid and binding, reinforcing an important message for buyers: if you receive a termination notice, it is worth getting legal advice before assuming your contract is over. What Is an Off-the-Plan Property? An off-the-plan property is a property purchased before construction is complete. Instead of buying an existing apartment, townhouse or home, the buyer enters into a contract based on plans, specifications and development documents. This type of purchase can appeal to buyers who want to secure a property early, plan a future move, arrange finance over time or invest before a project is complete. However, because construction and registration can take months or even years, off-the-plan contracts often include strict timelines and conditions that buyers need to understand before settlement. What Is a Sunset Clause? A sunset clause sets a deadline for important steps in a development to be completed. In an off-the-plan contract, this may include registration of the plan, creation of title, completion of construction or settlement. If the deadline passes and the required steps have not happened, the contract may give one or both parties a right to end the contract. However, that right is not always automatic – especially where a developer is relying on the clause to cancel the contract. The wording of the contract, the reason for the delay and any relevant legal requirements all need to be carefully considered. A Recent Win for Property Buyers CJM Lawyers recently acted for one of the purchasers in Supreme Court proceedings concerning the Chevron One development on the Gold Coast. The purchasers had entered into off-the-plan contracts in 2021, with settlement to occur by dates set several years later. When those dates passed, the developer sought to end the contracts. The buyers refused to accept the terminations and took the matter to the Supreme Court. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Queensland Supreme Court declared the contracts valid and binding. Critically, the Court found no basis for allowing the developer to benefit from its own breach of contract. The developer's attempt to point to pandemic-related supply chain disruptions as justification for termination was also rejected. What Should Buyers Do If a Developer Tries to Terminate? If a developer sends you a sunset clause termination notice, do not assume your contract is over. Whether the termination is valid may depend on the wording of the contract, the reason for the delay, the timing of the notice and the steps taken by each party. You should seek legal advice as soon as possible if your development has experienced lengthy delays, you have received a termination notice, a developer is relying on a sunset clause, or you are unsure whether your contract is still binding. Getting advice early can help you understand your rights before you accept a refund, sign documents or make decisions that may affect your legal position. How CJM Lawyers Can Help CJM Lawyers can assist buyers with off-the-plan property disputes, sunset clause issues and proposed contract terminations. Our Litigation team can review your contract and supporting documents, assess whether a termination is likely to be valid, explain your options, negotiate with developers and represent you in court proceedings where necessary. If your developer is trying to cancel your off-the-plan contract, speak with CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
Show More

Our Client Say

Our Client Say

Our Client Say