Immigration Law Article

Savannah Barrios
Australia Flag with passport and airplane

If you are seeking to visit, work, study or live in Australia, it is expected that you research and identify which visa would be most appropriate for your purposes of travel. For non-English speaking individuals, the process to find a suitable visa and apply for it may become unnecessarily confusing. The four most common types of visas available to non-Australian visa applicants, highlighting their eligibility, costs and entitlements. These visas include:

  1. Tourist visas;
  2. Working Holiday visas;
  3. Student visas;
  4. Partner visas; and
  5. Skilled visas.


This article provides a brief explanation in relation to Partner visas and Skilled visas.


Partner visas

If you are the de factor partner or spouse of an Australian citizen, Australian permanent resident or eligible New Zealand citizen living in Australia temporarily, you may be eligible to apply for the Partner visa (subclasses 309 and 100).


If you have not yet held a Partner visa of any kind, you must first apply for the temporary Partner (Provisional) visa (subclass 309). This visa allows you to temporarily stay in Australia until you are either granted a permanent Partner visa (subclass 100), or until you withdraw your application. Importantly, you must be outside of Australia when making this application. Once the Partner (Provisional) visa (subclass 309) has been granted, you will be allowed to reside in Australia and will be required to provide 2 years of ongoing documentation to prove a genuine relationship with your partner before being granted permanent residency through the Partner visa (subclass 100). The cost of applying for the Partner (Provisional) visa (subclass 309) is $8,850.00 (AUD), with an additional fee applied for each family member applying for the visa with you. While this amount is quite large, this does also cover the cost for your permanent Partner visa (subclass 100).


Whilst under either a provisional or permanent Partner visa, you are eligible to not only stay in Australia, but work, study, apply for Medicare, attend free English language classes, and travel to and from Australia as many times as you want.


Skilled visas

Australia's skilled migration program offers various avenues for individuals and families seeking permanent residency. Among the prominent options are the Subclass 189 and Subclass 190 visas, both points tested and not requiring employer sponsorship. The Subclass 189 is independent, while the Subclass 190 necessitates sponsorship from a state or territory. Applicants must attain a minimum of 65 points, which are allocated based on criteria like age, English proficiency, and work experience. Additionally, the Subclass 491 caters to skilled workers in specific regional areas, mandating sponsorship from a state or eligible family member. Furthermore, the Subclass 186 facilitates employer nomination for permanent residency, whereas the Subclass 494 serves as a regional variant. The Subclass 482 addresses temporary skill shortages through employer sponsorship, while the Subclass 485 allows international students to undertake post-graduation work. Each visa category entails distinct eligibility requirements and application procedures, offering diverse pathways for skilled migration to Australia. Generally visa application fees for these visas can range from approximately $1,500 (AUD) to $5,000 (AUD) for the main applicant.


These visas share a focus on addressing skill shortages and attracting skilled individuals to contribute to Australia's economy. With sectors like healthcare and IT experiencing shortages, skilled migrants bolster growth and innovation. Our country's allure lies in its high living standards, quality education, healthcare, diverse culture and scenic landscapes, making it a sought-after destination for those seeking improved opportunities and quality of life.


How we can help?

If you are considering applying for a visa to visit, work, study or live in Australia, the team at CJM Lawyers are here to help. Our immigration solicitors who are experienced in migration matters, including visa applications, are more than happy to assist throughout each step of the application process. To make matters more stress-free, many of our team are fluent in more than one language including Japanese, Korean, Mandarin, Spanish and French making it easier for you to gain a full understanding of the application process. If you seek assistance with your visa, please do not hesitate to contact Jake Jeong, head of our immigration team on 1300 245 299.


Disclaimer: This article is for general understanding and should not be used as a substitute for professional legal advice. Any reliance on the information is strictly at the user's risk, and there is no intention to create a lawyer-client relationship from this general communication.


Contact Us Now!

For comprehensive legal services, 
book now for your free initial consultation.

Contact Us

Book Now!

Property & Conveyancing
Guarantor  Advice
Commercial & Business
Wills and Estates
Building Disputes
Employment Law
Corporate & Commercial 
Litigation
Regulatory Compliance
Immigration
Litigation
Insolvency & Bankruptcy

Contact Us Now!

For comprehensive legal services, 
book now for your free initial consultation.

Contact Us

Book Us Now!

Property & Conveyancing
Guarantor  Advice
Commercial & Business
Wills and Estates
Building Disputes
Employment Law
Corporate & Commercial 
Litigation
Regulatory Compliance
Retail & commercial leasing, business transactions, company & trust sales, property development, guarantor advice

Our Latest Story

By October 2026 Edition • 8 October 2026
Cash flow pressure, overdue tax and unpaid suppliers can build gradually, leaving company directors unsure whether the business is experiencing a temporary setback or may be insolvent. Recognising the warning signs and seeking advice early may preserve more options and help directors reduce their personal risk. A company is generally insolvent when it cannot pay its debts as and when they fall due. Financial difficulty does not always mean a business must close, but delays in seeking advice can reduce the restructuring options available, increase business losses and expose company directors to greater personal risk. Business Owner vs Company Director: What’s the Difference? A business owner is someone who owns all or part of a business, while a company director is formally appointed to manage a company and has specific legal responsibilities. In many small businesses, the owner is also a director, but this is not always the case – for example, a sole trader is a business owner but not a company director. Company directors are expected to stay informed about the company’s financial position and take action when warning signs emerge. Ignoring the problem or continuing to incur debts without a realistic ability to pay them may expose directors to serious consequences. Common Warning Signs of Insolvency Warning signs may include ongoing losses, poor cash flow, overdue tax or superannuation, suppliers being paid outside normal terms, increasing debt, difficulty collecting money owed to the business, reliance on personal funds, incomplete financial records, payment arrangements with selected creditors, demands or court documents and suppliers moving the company to cash-on-delivery terms. No single warning sign necessarily proves insolvency. However, directors should seek an immediate review of the company’s financial position when several signs occur together, debts cannot be paid on time or the company is relying on new borrowing or personal funds to meet existing obligations. What Are a Company Director’s Responsibilities? Company directors must understand the company’s operations and financial position, ensure proper records are kept and prevent the company from trading while insolvent. If insolvency is suspected, directors should investigate promptly and obtain appropriate accounting and legal advice. Directors should not rely solely on current bank balances. Cash flow forecasts, debts falling due, tax obligations, employee entitlements, available finance and the realistic recoverability of money owed to the company may all be relevant.  What Can Happen If a Company Trades While Insolvent? Continuing to incur debts while insolvent can lead to civil penalties, compensation claims and, in serious cases, criminal consequences. Directors may also face scrutiny over transactions made shortly before an external administration, including payments that unfairly favour one creditor or transfers that remove company assets for less than their true value. What Should Company Directors Do First? Company directors should bring the company’s financial records up to date, prepare a realistic cash flow forecast and identify debts that are already overdue or will shortly fall due. This information can help professional advisers assess whether the company can continue trading and which restructuring or external administration options may remain available. Directors should also avoid selectively paying creditors or transferring assets without advice, as those transactions may later be challenged. Professional advice should be sought before entering new commitments, using personal funds, granting security, selling assets or agreeing to arrangements that may affect creditors. Could the Business Be Restructured? Depending on the company’s circumstances, options may include informal negotiations with creditors, safe harbour planning, small business restructuring, voluntary administration or liquidation. The most appropriate pathway will depend on whether the underlying business is viable, the level and type of debt, available assets and the support of key stakeholders. Early advice is important because some options require careful planning and may no longer be available once the company has exhausted its cash or creditor support. How CJM Lawyers Can Help CJM Lawyers can advise company directors experiencing financial distress, assess legal risk, explain restructuring and external administration options and work alongside accountants and registered insolvency practitioners. We can also assist with creditor negotiations, statutory demands, court proceedings and disputes involving liquidators or company transactions. If your company is struggling to pay debts when they fall due, has overdue tax or superannuation, or is relying on personal funds to meet ongoing expenses, contact CJM Lawyers early. Timely advice may help clarify whether the company is insolvent, preserve restructuring options and reduce the risk of the situation becoming more difficult to manage. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By October 2026 Edition • 8 October 2026
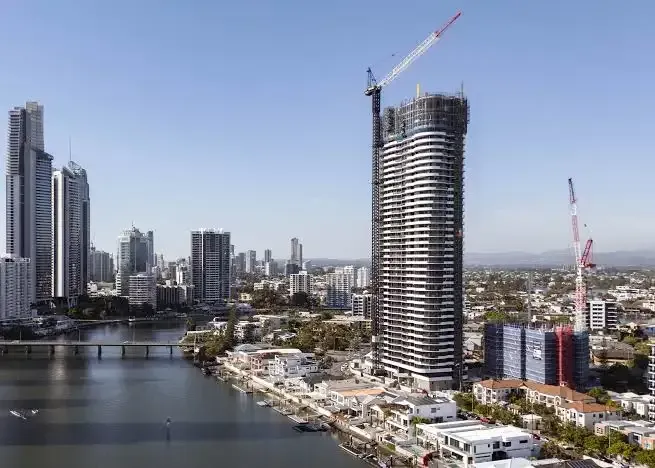
Received a termination notice from your developer? Before accepting a refund or assuming the contract is over, take steps to protect your position. When an off-the-plan development is delayed, a developer may seek to end the sale contract by relying on a sunset clause or another contractual right. The notice can appear final, but whether the termination is valid will depend on the contract, the circumstances surrounding the delay and the steps taken by each party. CJM Lawyers recently acted for a purchaser in successfully disputing a developer’s attempt to terminate an off-the-plan contract relating to the Chevron One development on the Gold Coast. The Queensland Supreme Court declared the contracts valid and binding, verifying why buyers should obtain advice before treating a termination notice as the end of a matter. 1. Do Not Immediately Accept a Refund or Sign Further Documents Accepting the return of your deposit, signing a release or agreeing that the contract has ended may affect the options available to you. Before responding, seek legal advice about what the notice means and whether the developer has a valid right to terminate. 2. Check the Deadline for Responding The notice or contract may contain strict timeframes. Record the date the notice was received and arrange an urgent review so that any response, objection or court application can be considered before a deadline passes. 3. Gather the Contract and All Supporting Documents Locate the signed contract, disclosure material, variations, extension notices, emails, letters and any updates about construction or registration. These documents can help establish what the parties agreed, what caused the delay and whether the required process was followed. 4. Review the Sunset Clause and Termination Wording A sunset date passing does not necessarily mean a developer can automatically cancel. The exact wording of the contract, any notice requirements and the relevant law must be considered together. 5. Create a Timeline of the Development Prepare a simple timeline recording key dates, promised completion dates, extensions, reported causes of delay and communications from the developer. This can help us assess whether the developer contributed to the delay or complied with its obligations. 6. Be Clear About the Outcome You Want Some buyers want the contract to remain on foot so they can complete the purchase. Others may prefer to exit and recover their deposit. Your preferred outcome will help shape the legal and commercial strategy. 7. Obtain Legal Advice Early Early advice can help you understand whether the termination is likely to be valid, identify urgent steps and avoid actions that could weaken your position. Depending on the circumstances, options may include disputing the notice, negotiating with the developer or seeking court orders. How CJM Lawyers Can Help CJM Lawyers can review your off-the-plan contract, termination notice and supporting documents, explain your options and communicate with the developer on your behalf. Our Litigation team can also represent you in negotiations and court proceedings where necessary. If a developer is trying to cancel your off-the-plan contract, contact CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By September 2026 Edition • 10 September 2026
Bought off-the-plan and the developer is trying to cancel your contract? Don’t assume it’s the end of the road. Buying property is exciting, but buying off the plan comes with a unique risk: you are committing to a home or investment before it has been built. If completion is delayed and the developer later tries to walk away from the contract, buyers can be left uncertain about their rights, their deposit and the property they hoped to secure. That issue was recently considered by the Queensland Supreme Court in a case involving Chevron One Apartments on the Gold Coast, Queensland. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Court declared the contracts valid and binding, reinforcing an important message for buyers: if you receive a termination notice, it is worth getting legal advice before assuming your contract is over. What Is an Off-the-Plan Property? An off-the-plan property is a property purchased before construction is complete. Instead of buying an existing apartment, townhouse or home, the buyer enters into a contract based on plans, specifications and development documents. This type of purchase can appeal to buyers who want to secure a property early, plan a future move, arrange finance over time or invest before a project is complete. However, because construction and registration can take months or even years, off-the-plan contracts often include strict timelines and conditions that buyers need to understand before settlement. What Is a Sunset Clause? A sunset clause sets a deadline for important steps in a development to be completed. In an off-the-plan contract, this may include registration of the plan, creation of title, completion of construction or settlement. If the deadline passes and the required steps have not happened, the contract may give one or both parties a right to end the contract. However, that right is not always automatic – especially where a developer is relying on the clause to cancel the contract. The wording of the contract, the reason for the delay and any relevant legal requirements all need to be carefully considered. A Recent Win for Property Buyers CJM Lawyers recently acted for one of the purchasers in Supreme Court proceedings concerning the Chevron One development on the Gold Coast. The purchasers had entered into off-the-plan contracts in 2021, with settlement to occur by dates set several years later. When those dates passed, the developer sought to end the contracts. The buyers refused to accept the terminations and took the matter to the Supreme Court. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Queensland Supreme Court declared the contracts valid and binding. Critically, the Court found no basis for allowing the developer to benefit from its own breach of contract. The developer's attempt to point to pandemic-related supply chain disruptions as justification for termination was also rejected. What Should Buyers Do If a Developer Tries to Terminate? If a developer sends you a sunset clause termination notice, do not assume your contract is over. Whether the termination is valid may depend on the wording of the contract, the reason for the delay, the timing of the notice and the steps taken by each party. You should seek legal advice as soon as possible if your development has experienced lengthy delays, you have received a termination notice, a developer is relying on a sunset clause, or you are unsure whether your contract is still binding. Getting advice early can help you understand your rights before you accept a refund, sign documents or make decisions that may affect your legal position. How CJM Lawyers Can Help CJM Lawyers can assist buyers with off-the-plan property disputes, sunset clause issues and proposed contract terminations. Our Litigation team can review your contract and supporting documents, assess whether a termination is likely to be valid, explain your options, negotiate with developers and represent you in court proceedings where necessary. If your developer is trying to cancel your off-the-plan contract, speak with CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
Show More

Our Latest Story

By October 2026 Edition • 8 October 2026
Cash flow pressure, overdue tax and unpaid suppliers can build gradually, leaving company directors unsure whether the business is experiencing a temporary setback or may be insolvent. Recognising the warning signs and seeking advice early may preserve more options and help directors reduce their personal risk. A company is generally insolvent when it cannot pay its debts as and when they fall due. Financial difficulty does not always mean a business must close, but delays in seeking advice can reduce the restructuring options available, increase business losses and expose company directors to greater personal risk. Business Owner vs Company Director: What’s the Difference? A business owner is someone who owns all or part of a business, while a company director is formally appointed to manage a company and has specific legal responsibilities. In many small businesses, the owner is also a director, but this is not always the case – for example, a sole trader is a business owner but not a company director. Company directors are expected to stay informed about the company’s financial position and take action when warning signs emerge. Ignoring the problem or continuing to incur debts without a realistic ability to pay them may expose directors to serious consequences. Common Warning Signs of Insolvency Warning signs may include ongoing losses, poor cash flow, overdue tax or superannuation, suppliers being paid outside normal terms, increasing debt, difficulty collecting money owed to the business, reliance on personal funds, incomplete financial records, payment arrangements with selected creditors, demands or court documents and suppliers moving the company to cash-on-delivery terms. No single warning sign necessarily proves insolvency. However, directors should seek an immediate review of the company’s financial position when several signs occur together, debts cannot be paid on time or the company is relying on new borrowing or personal funds to meet existing obligations. What Are a Company Director’s Responsibilities? Company directors must understand the company’s operations and financial position, ensure proper records are kept and prevent the company from trading while insolvent. If insolvency is suspected, directors should investigate promptly and obtain appropriate accounting and legal advice. Directors should not rely solely on current bank balances. Cash flow forecasts, debts falling due, tax obligations, employee entitlements, available finance and the realistic recoverability of money owed to the company may all be relevant.  What Can Happen If a Company Trades While Insolvent? Continuing to incur debts while insolvent can lead to civil penalties, compensation claims and, in serious cases, criminal consequences. Directors may also face scrutiny over transactions made shortly before an external administration, including payments that unfairly favour one creditor or transfers that remove company assets for less than their true value. What Should Company Directors Do First? Company directors should bring the company’s financial records up to date, prepare a realistic cash flow forecast and identify debts that are already overdue or will shortly fall due. This information can help professional advisers assess whether the company can continue trading and which restructuring or external administration options may remain available. Directors should also avoid selectively paying creditors or transferring assets without advice, as those transactions may later be challenged. Professional advice should be sought before entering new commitments, using personal funds, granting security, selling assets or agreeing to arrangements that may affect creditors. Could the Business Be Restructured? Depending on the company’s circumstances, options may include informal negotiations with creditors, safe harbour planning, small business restructuring, voluntary administration or liquidation. The most appropriate pathway will depend on whether the underlying business is viable, the level and type of debt, available assets and the support of key stakeholders. Early advice is important because some options require careful planning and may no longer be available once the company has exhausted its cash or creditor support. How CJM Lawyers Can Help CJM Lawyers can advise company directors experiencing financial distress, assess legal risk, explain restructuring and external administration options and work alongside accountants and registered insolvency practitioners. We can also assist with creditor negotiations, statutory demands, court proceedings and disputes involving liquidators or company transactions. If your company is struggling to pay debts when they fall due, has overdue tax or superannuation, or is relying on personal funds to meet ongoing expenses, contact CJM Lawyers early. Timely advice may help clarify whether the company is insolvent, preserve restructuring options and reduce the risk of the situation becoming more difficult to manage. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By October 2026 Edition • 8 October 2026
Received a termination notice from your developer? Before accepting a refund or assuming the contract is over, take steps to protect your position. When an off-the-plan development is delayed, a developer may seek to end the sale contract by relying on a sunset clause or another contractual right. The notice can appear final, but whether the termination is valid will depend on the contract, the circumstances surrounding the delay and the steps taken by each party. CJM Lawyers recently acted for a purchaser in successfully disputing a developer’s attempt to terminate an off-the-plan contract relating to the Chevron One development on the Gold Coast. The Queensland Supreme Court declared the contracts valid and binding, verifying why buyers should obtain advice before treating a termination notice as the end of a matter. 1. Do Not Immediately Accept a Refund or Sign Further Documents Accepting the return of your deposit, signing a release or agreeing that the contract has ended may affect the options available to you. Before responding, seek legal advice about what the notice means and whether the developer has a valid right to terminate. 2. Check the Deadline for Responding The notice or contract may contain strict timeframes. Record the date the notice was received and arrange an urgent review so that any response, objection or court application can be considered before a deadline passes. 3. Gather the Contract and All Supporting Documents Locate the signed contract, disclosure material, variations, extension notices, emails, letters and any updates about construction or registration. These documents can help establish what the parties agreed, what caused the delay and whether the required process was followed. 4. Review the Sunset Clause and Termination Wording A sunset date passing does not necessarily mean a developer can automatically cancel. The exact wording of the contract, any notice requirements and the relevant law must be considered together. 5. Create a Timeline of the Development Prepare a simple timeline recording key dates, promised completion dates, extensions, reported causes of delay and communications from the developer. This can help us assess whether the developer contributed to the delay or complied with its obligations. 6. Be Clear About the Outcome You Want Some buyers want the contract to remain on foot so they can complete the purchase. Others may prefer to exit and recover their deposit. Your preferred outcome will help shape the legal and commercial strategy. 7. Obtain Legal Advice Early Early advice can help you understand whether the termination is likely to be valid, identify urgent steps and avoid actions that could weaken your position. Depending on the circumstances, options may include disputing the notice, negotiating with the developer or seeking court orders. How CJM Lawyers Can Help CJM Lawyers can review your off-the-plan contract, termination notice and supporting documents, explain your options and communicate with the developer on your behalf. Our Litigation team can also represent you in negotiations and court proceedings where necessary. If a developer is trying to cancel your off-the-plan contract, contact CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By September 2026 Edition • 10 September 2026
Bought off-the-plan and the developer is trying to cancel your contract? Don’t assume it’s the end of the road. Buying property is exciting, but buying off the plan comes with a unique risk: you are committing to a home or investment before it has been built. If completion is delayed and the developer later tries to walk away from the contract, buyers can be left uncertain about their rights, their deposit and the property they hoped to secure. That issue was recently considered by the Queensland Supreme Court in a case involving Chevron One Apartments on the Gold Coast, Queensland. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Court declared the contracts valid and binding, reinforcing an important message for buyers: if you receive a termination notice, it is worth getting legal advice before assuming your contract is over. What Is an Off-the-Plan Property? An off-the-plan property is a property purchased before construction is complete. Instead of buying an existing apartment, townhouse or home, the buyer enters into a contract based on plans, specifications and development documents. This type of purchase can appeal to buyers who want to secure a property early, plan a future move, arrange finance over time or invest before a project is complete. However, because construction and registration can take months or even years, off-the-plan contracts often include strict timelines and conditions that buyers need to understand before settlement. What Is a Sunset Clause? A sunset clause sets a deadline for important steps in a development to be completed. In an off-the-plan contract, this may include registration of the plan, creation of title, completion of construction or settlement. If the deadline passes and the required steps have not happened, the contract may give one or both parties a right to end the contract. However, that right is not always automatic – especially where a developer is relying on the clause to cancel the contract. The wording of the contract, the reason for the delay and any relevant legal requirements all need to be carefully considered. A Recent Win for Property Buyers CJM Lawyers recently acted for one of the purchasers in Supreme Court proceedings concerning the Chevron One development on the Gold Coast. The purchasers had entered into off-the-plan contracts in 2021, with settlement to occur by dates set several years later. When those dates passed, the developer sought to end the contracts. The buyers refused to accept the terminations and took the matter to the Supreme Court. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Queensland Supreme Court declared the contracts valid and binding. Critically, the Court found no basis for allowing the developer to benefit from its own breach of contract. The developer's attempt to point to pandemic-related supply chain disruptions as justification for termination was also rejected. What Should Buyers Do If a Developer Tries to Terminate? If a developer sends you a sunset clause termination notice, do not assume your contract is over. Whether the termination is valid may depend on the wording of the contract, the reason for the delay, the timing of the notice and the steps taken by each party. You should seek legal advice as soon as possible if your development has experienced lengthy delays, you have received a termination notice, a developer is relying on a sunset clause, or you are unsure whether your contract is still binding. Getting advice early can help you understand your rights before you accept a refund, sign documents or make decisions that may affect your legal position. How CJM Lawyers Can Help CJM Lawyers can assist buyers with off-the-plan property disputes, sunset clause issues and proposed contract terminations. Our Litigation team can review your contract and supporting documents, assess whether a termination is likely to be valid, explain your options, negotiate with developers and represent you in court proceedings where necessary. If your developer is trying to cancel your off-the-plan contract, speak with CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
Show More

Our Latest Story

By October 2026 Edition • 8 October 2026
Cash flow pressure, overdue tax and unpaid suppliers can build gradually, leaving company directors unsure whether the business is experiencing a temporary setback or may be insolvent. Recognising the warning signs and seeking advice early may preserve more options and help directors reduce their personal risk. A company is generally insolvent when it cannot pay its debts as and when they fall due. Financial difficulty does not always mean a business must close, but delays in seeking advice can reduce the restructuring options available, increase business losses and expose company directors to greater personal risk. Business Owner vs Company Director: What’s the Difference? A business owner is someone who owns all or part of a business, while a company director is formally appointed to manage a company and has specific legal responsibilities. In many small businesses, the owner is also a director, but this is not always the case – for example, a sole trader is a business owner but not a company director. Company directors are expected to stay informed about the company’s financial position and take action when warning signs emerge. Ignoring the problem or continuing to incur debts without a realistic ability to pay them may expose directors to serious consequences. Common Warning Signs of Insolvency Warning signs may include ongoing losses, poor cash flow, overdue tax or superannuation, suppliers being paid outside normal terms, increasing debt, difficulty collecting money owed to the business, reliance on personal funds, incomplete financial records, payment arrangements with selected creditors, demands or court documents and suppliers moving the company to cash-on-delivery terms. No single warning sign necessarily proves insolvency. However, directors should seek an immediate review of the company’s financial position when several signs occur together, debts cannot be paid on time or the company is relying on new borrowing or personal funds to meet existing obligations. What Are a Company Director’s Responsibilities? Company directors must understand the company’s operations and financial position, ensure proper records are kept and prevent the company from trading while insolvent. If insolvency is suspected, directors should investigate promptly and obtain appropriate accounting and legal advice. Directors should not rely solely on current bank balances. Cash flow forecasts, debts falling due, tax obligations, employee entitlements, available finance and the realistic recoverability of money owed to the company may all be relevant.  What Can Happen If a Company Trades While Insolvent? Continuing to incur debts while insolvent can lead to civil penalties, compensation claims and, in serious cases, criminal consequences. Directors may also face scrutiny over transactions made shortly before an external administration, including payments that unfairly favour one creditor or transfers that remove company assets for less than their true value. What Should Company Directors Do First? Company directors should bring the company’s financial records up to date, prepare a realistic cash flow forecast and identify debts that are already overdue or will shortly fall due. This information can help professional advisers assess whether the company can continue trading and which restructuring or external administration options may remain available. Directors should also avoid selectively paying creditors or transferring assets without advice, as those transactions may later be challenged. Professional advice should be sought before entering new commitments, using personal funds, granting security, selling assets or agreeing to arrangements that may affect creditors. Could the Business Be Restructured? Depending on the company’s circumstances, options may include informal negotiations with creditors, safe harbour planning, small business restructuring, voluntary administration or liquidation. The most appropriate pathway will depend on whether the underlying business is viable, the level and type of debt, available assets and the support of key stakeholders. Early advice is important because some options require careful planning and may no longer be available once the company has exhausted its cash or creditor support. How CJM Lawyers Can Help CJM Lawyers can advise company directors experiencing financial distress, assess legal risk, explain restructuring and external administration options and work alongside accountants and registered insolvency practitioners. We can also assist with creditor negotiations, statutory demands, court proceedings and disputes involving liquidators or company transactions. If your company is struggling to pay debts when they fall due, has overdue tax or superannuation, or is relying on personal funds to meet ongoing expenses, contact CJM Lawyers early. Timely advice may help clarify whether the company is insolvent, preserve restructuring options and reduce the risk of the situation becoming more difficult to manage. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By October 2026 Edition • 8 October 2026
Received a termination notice from your developer? Before accepting a refund or assuming the contract is over, take steps to protect your position. When an off-the-plan development is delayed, a developer may seek to end the sale contract by relying on a sunset clause or another contractual right. The notice can appear final, but whether the termination is valid will depend on the contract, the circumstances surrounding the delay and the steps taken by each party. CJM Lawyers recently acted for a purchaser in successfully disputing a developer’s attempt to terminate an off-the-plan contract relating to the Chevron One development on the Gold Coast. The Queensland Supreme Court declared the contracts valid and binding, verifying why buyers should obtain advice before treating a termination notice as the end of a matter. 1. Do Not Immediately Accept a Refund or Sign Further Documents Accepting the return of your deposit, signing a release or agreeing that the contract has ended may affect the options available to you. Before responding, seek legal advice about what the notice means and whether the developer has a valid right to terminate. 2. Check the Deadline for Responding The notice or contract may contain strict timeframes. Record the date the notice was received and arrange an urgent review so that any response, objection or court application can be considered before a deadline passes. 3. Gather the Contract and All Supporting Documents Locate the signed contract, disclosure material, variations, extension notices, emails, letters and any updates about construction or registration. These documents can help establish what the parties agreed, what caused the delay and whether the required process was followed. 4. Review the Sunset Clause and Termination Wording A sunset date passing does not necessarily mean a developer can automatically cancel. The exact wording of the contract, any notice requirements and the relevant law must be considered together. 5. Create a Timeline of the Development Prepare a simple timeline recording key dates, promised completion dates, extensions, reported causes of delay and communications from the developer. This can help us assess whether the developer contributed to the delay or complied with its obligations. 6. Be Clear About the Outcome You Want Some buyers want the contract to remain on foot so they can complete the purchase. Others may prefer to exit and recover their deposit. Your preferred outcome will help shape the legal and commercial strategy. 7. Obtain Legal Advice Early Early advice can help you understand whether the termination is likely to be valid, identify urgent steps and avoid actions that could weaken your position. Depending on the circumstances, options may include disputing the notice, negotiating with the developer or seeking court orders. How CJM Lawyers Can Help CJM Lawyers can review your off-the-plan contract, termination notice and supporting documents, explain your options and communicate with the developer on your behalf. Our Litigation team can also represent you in negotiations and court proceedings where necessary. If a developer is trying to cancel your off-the-plan contract, contact CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
By September 2026 Edition • 10 September 2026
Bought off-the-plan and the developer is trying to cancel your contract? Don’t assume it’s the end of the road. Buying property is exciting, but buying off the plan comes with a unique risk: you are committing to a home or investment before it has been built. If completion is delayed and the developer later tries to walk away from the contract, buyers can be left uncertain about their rights, their deposit and the property they hoped to secure. That issue was recently considered by the Queensland Supreme Court in a case involving Chevron One Apartments on the Gold Coast, Queensland. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Court declared the contracts valid and binding, reinforcing an important message for buyers: if you receive a termination notice, it is worth getting legal advice before assuming your contract is over. What Is an Off-the-Plan Property? An off-the-plan property is a property purchased before construction is complete. Instead of buying an existing apartment, townhouse or home, the buyer enters into a contract based on plans, specifications and development documents. This type of purchase can appeal to buyers who want to secure a property early, plan a future move, arrange finance over time or invest before a project is complete. However, because construction and registration can take months or even years, off-the-plan contracts often include strict timelines and conditions that buyers need to understand before settlement. What Is a Sunset Clause? A sunset clause sets a deadline for important steps in a development to be completed. In an off-the-plan contract, this may include registration of the plan, creation of title, completion of construction or settlement. If the deadline passes and the required steps have not happened, the contract may give one or both parties a right to end the contract. However, that right is not always automatic – especially where a developer is relying on the clause to cancel the contract. The wording of the contract, the reason for the delay and any relevant legal requirements all need to be carefully considered. A Recent Win for Property Buyers CJM Lawyers recently acted for one of the purchasers in Supreme Court proceedings concerning the Chevron One development on the Gold Coast. The purchasers had entered into off-the-plan contracts in 2021, with settlement to occur by dates set several years later. When those dates passed, the developer sought to end the contracts. The buyers refused to accept the terminations and took the matter to the Supreme Court. CJM Lawyers acted for one of the purchasers in successfully disputing the developer’s right to terminate. The Queensland Supreme Court declared the contracts valid and binding. Critically, the Court found no basis for allowing the developer to benefit from its own breach of contract. The developer's attempt to point to pandemic-related supply chain disruptions as justification for termination was also rejected. What Should Buyers Do If a Developer Tries to Terminate? If a developer sends you a sunset clause termination notice, do not assume your contract is over. Whether the termination is valid may depend on the wording of the contract, the reason for the delay, the timing of the notice and the steps taken by each party. You should seek legal advice as soon as possible if your development has experienced lengthy delays, you have received a termination notice, a developer is relying on a sunset clause, or you are unsure whether your contract is still binding. Getting advice early can help you understand your rights before you accept a refund, sign documents or make decisions that may affect your legal position. How CJM Lawyers Can Help CJM Lawyers can assist buyers with off-the-plan property disputes, sunset clause issues and proposed contract terminations. Our Litigation team can review your contract and supporting documents, assess whether a termination is likely to be valid, explain your options, negotiate with developers and represent you in court proceedings where necessary. If your developer is trying to cancel your off-the-plan contract, speak with CJM Lawyers before accepting a refund, signing further documents or walking away from a property you still want to secure. Disclaimer: This article provides general information only and does not constitute legal advice. The information may not apply to your circumstances and should not be relied on as a substitute for tailored legal advice. If you need advice, please contact CJM Lawyers to speak with one of our legal professionals.
Show More

Our Client Say

Our Client Say
Our Client Say